Author: David Olsen

Florida Probate After a Death

CSG FLORIDA LEGAL AUTHORITY

7 Deadlines and Duties Families Should Know

Written by Robert Mellinger, Esq.

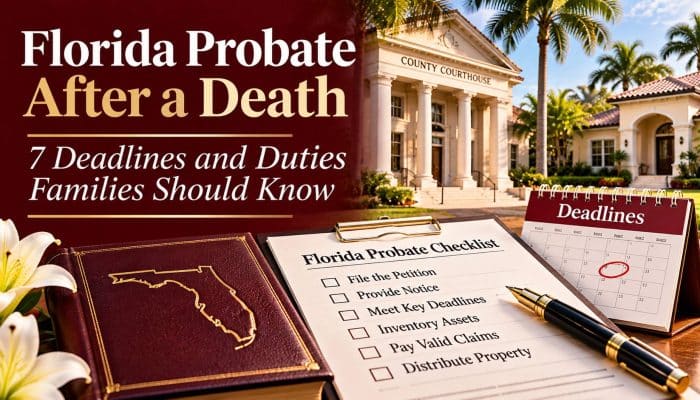
After a family member dies, Florida probate can feel like a maze of paperwork and deadlines at exactly the time a family is least prepared to deal with them. Some deadlines begin with the death itself. Others begin only after a notice is served, a probate case is opened, or a Notice To Creditors is published or a creditor receives notice.

The most important practical lesson is simple: do not assume that “nothing needs to be done yet.” Florida law imposes duties on the custodian of a Will, gives beneficiaries and creditors limited periods to act, and places fiduciary obligations on the personal representative once appointed.

KEY TAKEAWAY

Florida probate does not have one universal deadline. Different rights run from different triggering events. The original Will generally must be deposited within 10 days after the custodian learns of the death; objections after a Notice of Administration have their own limits; exempt-property rights can be waived if not timely asserted; creditor claims are subject to separate statutory bars; and the personal representative has an ongoing fiduciary duty to administer the estate efficiently and in the best interests of interested persons.

1. The Original Will: The 10-Day Rule

One of the earliest Florida probate duties can arise before a probate case is even opened. Under Florida Statute § 732.901, the custodian of a Will must deposit the Will with the clerk of the court having venue of the decedent’s estate within 10 days after receiving information that the testator is dead.

The custodian must also supply the testator’s date of death or the last four digits of the testator’s Social Security number to the clerk when depositing the Will. If the custodian fails to deposit the Will without just or reasonable cause, a court may compel production and may assess costs, damages, and a reasonable attorney’s fee against the delinquent custodian.

For families, this means the original Will should be located promptly. A photocopy stored on a phone or computer is not a substitute for locating the original instrument when one exists.

2. Opening Probate: Who Can Start the Case?

Florida Statute § 733.202 provides that any interested person may petition for administration. The person named as personal representative in the Will often takes the lead, but the statute is not limited to that person.

Opening probate is more than filing a document. The court must determine whether a Will should be admitted, whether the proposed personal representative is qualified, and what notices and administration procedures are required. A self-proved Will may generally be admitted without additional proof under § 733.201, while other circumstances can require witness testimony or other proof.

3. Notice of Administration Can Start Important Objection Deadlines

Once a formal administration is underway, the Notice of Administration can trigger significant deadlines. Section 733.212 addresses service of the notice and the time for certain objections involving the validity of the Will, venue, and jurisdiction.

The current statute contains strict limitations and expressly states that certain periods may not be extended for reasons such as affirmative representation, failure to disclose information, or misconduct. Depending on the particular objection and circumstances, additional statutory outside limits may also apply.

A beneficiary who receives a Notice of Administration should therefore read it immediately rather than putting it aside with routine estate correspondence.

4. Exempt Property Has Its Own Deadline

Florida law protects certain categories of property for qualifying family members, but those rights are not necessarily self-executing forever. Section 733.212 states that persons who may be entitled to exempt property under § 732.402 can be deemed to have waived those rights unless a petition for determination of exempt property is timely filed.

The general deadline stated in the Notice of Administration statute is the later of four months after service of the Notice of Administration on the person or 40 days after termination of specified proceedings involving the Will or other matters affecting the exempt property.

This is a good example of why families should not treat all probate assets alike. Homestead, exempt property, family allowance, probate assets, and nonprobate transfers can involve different rules.

5. Creditors Have a Separate Claims Process

Creditor claims are governed primarily by Part VII of Chapter 733. The personal representative must address Notice to Creditors, claims, objections, priority, and payment under the applicable statutes.

Florida probate creditor law includes both shorter claim periods associated with publication or service of notice and an outside statutory bar. Whether a particular claim is timely can depend on the creditor, the type of claim, whether proper notice was given, and other statutory exceptions.

For that reason, a personal representative should not simply pay whichever bills arrive first. Claims must be evaluated within the statutory administration process, and distributions to beneficiaries should be coordinated with valid estate obligations.

6. The Personal Representative Is a Fiduciary, Not Merely a Family Organizer

Once appointed, the personal representative assumes legal duties. Section 733.602 provides that a personal representative is a fiduciary and must observe standards of care applicable to trustees. The personal representative has a duty to settle and distribute the estate according to the Will and the Probate Code as expeditiously and efficiently as is consistent with the estate’s best interests.

The statute also directs the personal representative to use the authority granted by the Probate Code, the Will, and court orders for the best interests of interested persons, including creditors.

Practically, this means the personal representative should safeguard estate property, maintain records, identify assets and liabilities, coordinate required notices, avoid self-dealing, and refrain from premature distributions that could leave the estate unable to satisfy valid obligations.

7. Do Not Distribute the Estate Too Early

Families understandably want to transfer vehicles, close accounts, divide personal property, sell real estate, or distribute cash soon after a death. But probate administration is not simply a race to divide assets.

The personal representative must consider creditor rights, taxes, expenses of administration, protected family rights, the terms of the Will, court orders, and the interests of beneficiaries. A distribution that seems harmless can create problems if a valid claim or statutory right later must be satisfied.

Before substantial distributions are made, the personal representative should understand what assets are actually part of the probate estate, which obligations remain unresolved, and whether court approval or additional administration steps are required.

What About Property That Does Not Pass Through Probate?

Not every asset owned or controlled by a decedent necessarily becomes a probate asset. Property may pass by survivorship, beneficiary designation, trust, or another nonprobate mechanism. Florida homestead can also have special constitutional and statutory treatment.

That makes the first asset inventory especially important. Families should identify how each asset is titled and whether a beneficiary or survivorship arrangement exists before assuming that the Will controls it.

What If the Original Will Cannot Be Found?

A lost or destroyed Will can create a different probate problem. Florida Statute § 733.207 provides a procedure for establishing and admitting a lost or destroyed Will, but the evidentiary requirements are different from simply presenting the original document.

Families who find copies but cannot locate the original should avoid making assumptions about validity and should obtain legal advice before treating the estate as intestate.

A Practical First-30-Days Checklist

In the first weeks after a death, families should consider locating the original Will and estate-planning documents; obtaining certified death certificates; identifying the current deed to any Florida real estate; securing the residence and other property; identifying bank, investment, retirement, insurance, and business accounts; determining whether accounts have beneficiaries or survivorship features; gathering bills and creditor correspondence; preserving financial records; identifying the person nominated as personal representative; and obtaining probate advice before transferring or distributing substantial assets.

Where a surviving spouse, minor child, homestead, blended family, business interest, disputed Will, creditor issue, or substantial real estate is involved, early review is particularly important because additional statutory rights and deadlines may apply.

Why Families Get Into Trouble

Many probate problems do not begin with bad intentions. They begin with assumptions: “Mom’s Will says I get the house, so I can sell it;” “Dad owed that credit card, so I should pay it from my own account;” “We are all the children, so we can divide everything ourselves;” or “There is no hurry because probate can wait.”

Florida law may produce a different answer depending on title, homestead status, the Will, family relationships, creditor rights, and the type of asset involved. The safest approach is to identify the legal framework before irreversible steps are taken.

The Bottom Line

Florida probate is manageable when the family understands the sequence of events and treats deadlines seriously. The original Will should be addressed promptly. Notices should be read immediately. Creditor and beneficiary rights should be evaluated before distributions are made. And the personal representative should understand that the role carries fiduciary responsibilities, not merely administrative convenience.

At Caserta & Spiriti, PLLC, we assist Florida families with probate administration, elder law, estate planning, homestead issues, deeds, and related real estate matters. Early guidance can help families preserve rights, avoid missed deadlines, and move the estate toward an orderly resolution.

Disclaimer: This article is provided for general informational and educational purposes only and is not legal advice. Reading this article or receiving this e-mail does not create an attorney-client relationship. Probate rights and deadlines are fact-specific and may depend on the type of proceeding, the notice served, the family circumstances, the assets involved, and other facts.
Florida rental flood disclosure article illustration

Florida Rental Flood Disclosure

CSG FLORIDA LEGAL AUTHORITY

What Landlords and Tenants Need to Know About Florida Statute § 83.512

Written by Joseph Spiriti, Esq.

Florida landlords signing certain residential leases now have a specific flood-disclosure obligation that should be built into every compliant leasing workflow. For a residential rental agreement with a term of one year or longer, Florida Statute § 83.512 requires the landlord to give the prospective tenant a separate flood disclosure at or before the lease is executed.

KEY TAKEAWAY

For a Florida residential rental agreement with a term of one year or longer, the landlord must provide the prospective tenant a separate flood disclosure at or before execution. The disclosure addresses known flood damage during the landlord’s ownership, flood-related insurance claims, and flood assistance received.

Who Is Covered?

The statute applies when a landlord enters into a rental agreement for residential real property for a term of one year or longer. For covered transactions, the disclosure must be given at or before execution of the rental agreement.

A Separate Document Is Required

Section 83.512 expressly requires the disclosure in a separate document and in substantially the statutory form. Landlords and property managers should not assume that language buried inside a lengthy lease satisfies that requirement.

What Must Be Disclosed?

The statutory form warns that renters’ insurance policies do not include coverage for flood damage and encourages discussion of separate flood insurance with an insurance agent. The landlord must indicate whether the landlord knows of flooding that damaged the dwelling unit during ownership, whether an insurance claim relating to flood damage was filed, and whether flood assistance was received.

What Counts as Flooding?

The statute defines flooding to include specified inundation from overflow of inland or tidal waters, unusual and rapid accumulation of runoff or surface waters from an established water source, and sustained periods of standing water resulting from rainfall. The statutory definition—not casual usage—controls the disclosure.

What If the Disclosure Is Not Provided?

If the landlord violates § 83.512 and the tenant suffers substantial loss or damage to personal property as a result of flooding, the tenant may terminate the rental agreement by written notice and surrender possession no later than 30 days after the damage or loss. Termination becomes effective upon surrender of possession.

What Is Substantial Loss or Damage?

The statute defines substantial loss or damage as repair or replacement costs totaling 50 percent or more of the personal property’s market value on the date flooding occurred. Documentation of damaged property, value, repair costs, replacement costs and timing may therefore become important.

What Happens to Prepaid Rent?

Following a qualifying termination, the landlord must refund rent or other amounts paid in advance for periods after the effective termination date. The tenant remains liable for delinquent unpaid rent or other sums owed before termination.

Flood Disclosure Is Not the Same as a FEMA Flood-Zone Determination

The statutory form focuses on known flood damage during the landlord’s ownership, flood-related claims and flood assistance. Those subjects are not identical to whether the property lies within a particular mapped flood zone. Tenants concerned about flood exposure may independently investigate available flood information and consult an insurance professional.

Florida Also Has a Residential Sales Flood Disclosure

Section 689.302 separately addresses flood disclosure to prospective purchasers of residential real property. Although the rental and sales statutes address similar subjects, they govern different transactions. A landlord should use the rental disclosure required by Chapter 83 rather than substitute a sales form.

Practical Compliance Steps for Landlords

Determine whether the lease term is one year or longer; use the current statutory disclosure as a separate document; complete the questions accurately from actual knowledge and records; deliver it at or before lease execution; configure electronic-signature systems so delivery occurs on time; and preserve evidence of the completed disclosure and delivery.

Practical Steps for Tenants

Read the disclosure before signing. If it identifies prior flood damage, an insurance claim or flood assistance, consider asking additional questions and investigating flood risk. Keep the disclosure with the signed lease. If flooding later occurs, promptly document the event and damaged personal property and pay attention to statutory notice and timing requirements.

The Bottom Line

Florida’s rental flood-disclosure statute adds a specific pre-signing compliance step for covered residential leases. For landlords, the safest approach is a repeatable disclosure and documentation procedure. For tenants, the disclosure provides information that may matter when evaluating flood risk and insurance before committing to the tenancy.

At Caserta & Spiriti, PLLC, we assist Florida landlords, tenants, property owners and businesses with leases, landlord-tenant disputes, real estate contracts and related property matters.

Disclaimer: This article is provided for general informational and educational purposes only and is not legal advice. Reading it does not create an attorney-client relationship.

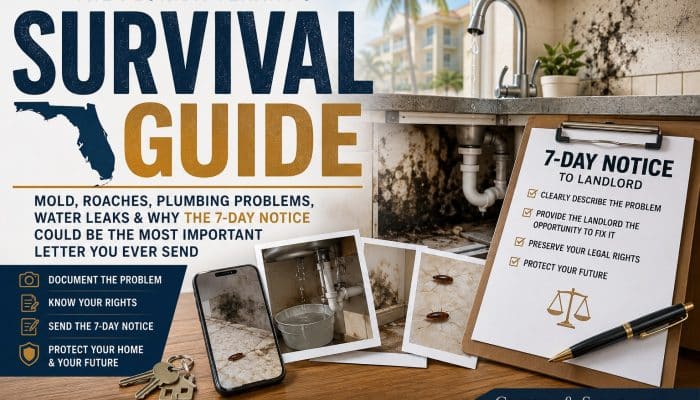
Florida tenant rights article illustration

Florida Tenant Rights: Mold, Plumbing Problems, Roaches, Termites & Why the 7-Day Notice Could Be the Most Important Letter You Ever Send

By Joseph A. Spiriti Jr., Esq.

Caserta & Spiriti, PLLC

Imagine coming home after a long day at work only to find water leaking through your ceiling, mold spreading behind your bathroom vanity, or roaches appearing in your kitchen despite repeated complaints to your landlord.

Like most tenants, your first instinct may be to pick up the phone, send a text message, or assume someone will eventually come out and fix the problem.

Sometimes they do.

Unfortunately, many times they don’t.

Mold: The Mold May Not Be the Real Legal Issue

One of the most common questions I receive is:

“Can I break my lease because there’s mold?”

The answer depends on several factors.

Interestingly, Florida’s Residential Landlord and Tenant Act does not specifically mention mold.

Instead, the legal analysis often focuses on what is causing the mold.

For example:

  • Is there a leaking roof?
  • A broken plumbing line?
  • Water intrusion around windows?
  • An air conditioning system creating excessive moisture?
  • A leak inside a wall that has gone unrepaired?

In many situations, the underlying water intrusion—not simply the visible mold itself—is what creates the legal issue.

That’s why I encourage tenants to describe the actual conditions in their written notice.

Don’t simply write:

“There’s mold.”

Instead, explain:

  • where the mold is located;
  • when you first noticed it;
  • whether it appears to be spreading;
  • whether water is actively leaking; and
  • what damage has occurred.

Specific facts help create a much clearer picture than general complaints.

Attorney’s Tip

If you’re considering making a claim involving mold, resist the urge to immediately throw away damaged items or begin extensive cleanup before documenting the condition.

Good photographs taken early often become some of the strongest evidence available later.

Roaches, Termites & Other Pest Problems

Nobody rents a home expecting to deal with cockroaches, termites, rats, or other pests.

Fortunately, Florida law generally places responsibility on landlords of many apartment and multi-family properties to make reasonable provisions for extermination of certain pests and wood-destroying organisms unless the responsibility has been lawfully modified in writing.

If extermination requires tenants to temporarily leave the property, Florida law also contains provisions governing notice, temporary relocation, and rent abatement in certain situations.

That said, one of the biggest mistakes I see is tenants assuming those same rules automatically apply to every rental home.

They don’t.

If you’re renting a single-family residence or duplex, the lease may allocate responsibilities differently.

Never assume.

Always verify.

Plumbing Leaks, Sewage Problems & Loss of Hot Water

Some maintenance issues are inconvenient.

Others become more serious with each passing day.

Water leaking behind walls can lead to structural damage.

Sewage backups may present sanitation concerns.

A lack of running water or hot water can substantially affect everyday living.

Florida law generally requires landlords to maintain plumbing in reasonable working condition and, in many apartment settings, provide running water and hot water as required by law.

The sooner these conditions are documented and reported in writing, the easier it often becomes to establish a clear timeline of events.

Waiting several weeks while hoping the problem resolves itself rarely helps anyone.

The One Document That Can Make—or Break—Your Case

If you’ve read this far, you’ve already learned about documenting problems, reviewing your lease, and putting concerns in writing.

Now let’s talk about what I believe is often the single most important document in a Florida landlord-tenant dispute.

The 7-Day Notice.

Many people think it’s simply another complaint letter.

It isn’t.

It is the statutory notice recognized by Florida law that often serves as the legal foundation for preserving a tenant’s rights while providing the landlord with the notice and opportunity to cure contemplated by law before certain legal remedies become available.

In my experience, judges frequently look at this document early in a case because it often tells the story of what happened, what the tenant complained about, and whether the landlord was given a fair opportunity to correct the problem.

Unfortunately, I’ve also seen otherwise legitimate claims become much more difficult because the notice contained avoidable mistakes.

Some of the most common include:

  • Sending the notice to the wrong person.
  • Failing to clearly describe the conditions.
  • Demanding relief not authorized under the circumstances.
  • Omitting important facts.
  • Using generic internet forms that don’t fit the situation.
  • Delivering the notice improperly.
  • Waiting too long to send it.

Each of these mistakes can affect the case.

Although Florida law generally does not require an attorney to prepare a 7-Day Notice, I strongly recommend having an experienced Florida landlord-tenant attorney prepare or review it whenever practical.

Not because attorneys have a “special form,” but because experience matters.

A properly prepared notice helps preserve important legal rights, clearly identifies the issues requiring repair, documents the landlord’s opportunity to cure, establishes a timeline of events, and may become one of the most important pieces of evidence if litigation later becomes necessary.

Simply put, the 7-Day Notice is much more than a letter.

It is often the document that lays the legal foundation for everything that follows.

What Should Be Included in a Florida 7-Day Notice?

No two landlord-tenant disputes are exactly alike. The facts, the lease, and the nature of the problem all matter. That’s why there is no “one-size-fits-all” notice that works in every situation.

Generally speaking, however, a properly prepared 7-Day Notice should clearly identify:

  • The tenant’s name and rental property address.
  • The date the notice is prepared.
  • The landlord or property manager receiving the notice.
  • A detailed description of each condition requiring attention.
  • When the problem first began, if known.
  • Any damage or health or safety concerns that have resulted.
  • A clear request that the landlord correct the condition within the time allowed by law.
  • When appropriate, the statutory remedy the tenant intends to pursue if the condition is not timely corrected.

One of the biggest mistakes I see is tenants relying on vague statements such as:

“The apartment is terrible.”

That tells the landlord—and, if litigation later becomes necessary, the court—very little.

A much stronger notice identifies the specific issues. For example:

  • Water is leaking beneath the kitchen sink and has damaged the cabinet flooring.
  • Mold has developed behind the bathroom vanity following an unrepaired plumbing leak.
  • The water heater has not produced hot water since a specific date.
  • Roaches continue to appear throughout the kitchen despite previous extermination efforts.

Specific facts are almost always more persuasive than general complaints.

Attorney’s Tip

Think of your notice as a professional business letter—not an emotional social media post.

Avoid exaggeration.

Avoid insults.

Avoid assumptions.

State the facts accurately, calmly, and completely. Credibility is one of your greatest assets if the matter later finds its way into a courtroom.

Before You Decide to Withhold Rent

Perhaps no subject creates more confusion than rent withholding.

I’ve had many clients tell me,

“My landlord hasn’t fixed anything, so I’m just going to stop paying rent.”

That decision can create serious legal consequences if the statutory procedures have not been followed.

Florida law provides certain remedies when a landlord materially fails to comply with legal obligations. However, those remedies generally depend upon proper notice being given and the applicable statutory requirements being satisfied. If litigation occurs, tenants may also be required to deposit rent into the court registry while the dispute is pending.

For that reason, I strongly encourage tenants not to withhold rent, terminate a lease, or move out without first understanding their legal rights and obligations.

The cost of making the wrong decision can far exceed the cost of obtaining legal advice beforehand.

When Your Landlord Doesn’t Follow the Rules

The vast majority of landlords want satisfied tenants and make reasonable efforts to address legitimate maintenance concerns.

Occasionally, however, disputes escalate.

If a landlord attempts to force a tenant out by changing the locks, disconnecting utilities, removing doors, or otherwise preventing access to the property without following Florida’s legal eviction process, the situation becomes much more serious.

Florida law generally prohibits these types of “self-help” eviction practices.

If something like this occurs, don’t simply argue with the landlord.

Document everything.

Preserve photographs, videos, emails, text messages, and any witness information.

Then speak with an experienced Florida landlord-tenant attorney as soon as practical to determine your legal options.

Eight Common Mistakes That Can Hurt an Otherwise Good Case

Over the years, I’ve seen many disputes become far more complicated because of mistakes that could have been avoided.

Some of the most common include:

  1. Waiting too long to report the problem.

    Small maintenance issues rarely improve by themselves.

  2. Complaining only by phone.

    Verbal conversations are difficult to prove later.

  3. Throwing away damaged property before documenting it.

    Always preserve evidence whenever practical.

  4. Sending an incomplete or vague notice.

    General complaints rarely tell the full story.

  5. Assuming every maintenance problem creates the same legal remedy.

    Different conditions may involve different legal rights.

  6. Ignoring the lease agreement.

    Many answers are found there.

  7. Downloading generic internet forms.

    A notice that worked for someone else’s situation may not be appropriate for yours.

  8. Acting out of frustration instead of strategy.

    Emotions are understandable.

    Good documentation and careful preparation usually produce better results.

Frequently Asked Questions

Can mold allow me to break my lease?

Possibly—but not automatically.

Whether a tenant may terminate a lease depends upon numerous factors, including the cause of the condition, whether the landlord materially failed to comply with applicable legal obligations, the language of the lease, and whether proper statutory notice was provided.

Every situation should be evaluated on its own facts.

Can I withhold rent because of roaches or plumbing problems?

Don’t assume you can.

Florida law establishes procedures that generally require proper written notice before certain remedies become available. Depending upon the circumstances, additional legal requirements may also apply.

If you’re considering withholding rent, speak with an experienced Florida landlord-tenant attorney first.

What if my landlord ignores my written notice?

The answer depends on the facts, the lease, the applicable statutes, and the specific condition involved.

If the required notice was properly prepared and delivered, additional legal remedies may become available depending upon the circumstances. An attorney can help evaluate those options.

Is an attorney required to prepare a 7-Day Notice?

No.

Florida law generally does not require an attorney to prepare the notice.

However, because the 7-Day Notice frequently becomes one of the most important documents in a landlord-tenant dispute, I strongly recommend having an experienced Florida landlord-tenant attorney prepare or review it whenever practical.

The notice is more than a letter. It is often the document that preserves rights, satisfies statutory notice requirements, provides the landlord with the opportunity to cure contemplated by law, and helps establish the foundation for any future legal action.

Getting it right the first time is almost always preferable to trying to correct mistakes after litigation begins.

Does every maintenance problem give me the right to terminate my lease?

No.

Florida law does not treat every maintenance issue the same way.

The severity of the condition, the lease agreement, the applicable statutes, and the facts surrounding the dispute all play important roles in determining what remedies, if any, may be available.

Final Thoughts

After more than three decades practicing landlord-tenant law throughout Florida, I’ve learned that most cases aren’t won or lost because someone had a stronger argument.

They’re won or lost because someone preserved—or failed to preserve—their rights from the very beginning.

The law gives landlords important rights.

It gives tenants important rights as well.

But it also requires both sides to follow certain procedures before asking a court to intervene.

If you’re dealing with mold, termites, roaches, plumbing failures, sewage backups, water intrusion, loss of hot water, or other serious maintenance concerns, don’t rely solely on phone calls or generic forms you find online.

Take photographs.

Keep detailed records.

Review your lease.

Communicate in writing.

And never underestimate the importance of a properly prepared 7-Day Notice.

Although an attorney is generally not required to prepare that notice, it is often the legal foundation upon which the rest of the case is built. A properly prepared notice not only helps preserve important legal rights, but also provides the landlord with the notice and opportunity to cure contemplated by Florida law before certain remedies may become available.

As I often tell my clients, it’s almost always easier—and far less expensive—to protect your rights at the beginning of a case than it is to repair avoidable mistakes after a dispute has escalated.

If you’re uncertain about your rights or how Florida law applies to your specific situation, consult with an experienced Florida landlord-tenant attorney before making decisions that could affect your legal remedies.

About the Author

Joseph A. Spiriti Jr., Esq. is a Florida attorney and partner with Caserta & Spiriti, PLLC, where he has represented landlords, tenants, homeowners, businesses, and property owners in a wide variety of Florida real estate and landlord-tenant matters for more than 30 years.

This article is provided for general educational purposes only and is not intended as legal advice. Reading this article does not create an attorney-client relationship. Every landlord-tenant matter depends upon its unique facts, the terms of the lease, and the notices exchanged between the parties. Individuals should consult with a qualified Florida attorney regarding their specific circumstances.

An Islamic Living Will in Florida: Protecting Your Medical Wishes With Faith-Aligned and Legally Compliant Planning

For Muslim individuals and families in Florida, advance medical planning involves both legal responsibility and religious guidance. An Islamic (Muslim) Living Will allows you to clearly document your medical wishes in a way that complies with Florida law while honoring the ethical and spiritual principles of Sharia (Islamic law). This combined directive helps ensure that your treatment, especially during critical or end-of-life moments, is handled according to Islamic values such as preservation of life (Hifz al-Nafs), human dignity, and the avoidance of unnecessary suffering.

This document is legally recognized in Florida and serves as an essential part of a comprehensive estate and incapacity plan for Muslims across the state.

What Is an Islamic Living Will?

An Islamic Living Will is a Florida advance directive that:

  • Meets Florida’s statutory requirements for a valid Living Will,
  • Outlines your medical treatment preferences under Islamic bioethics,
  • Appoints a healthcare surrogate who understands and will honor your religious beliefs, and
  • Ensures that any decisions made on your behalf reflect your faith and values.

It is important to understand that an Islamic Living Will is separate and distinct from a Last Will and Testament (Wasiyyah), which governs the distribution of assets after death. The Islamic Living Will is purely a medical decision-making document.

Key Legal Requirements for a Valid Living Will in Florida

Under Chapter 765, Florida Statutes, a Living Will must meet certain conditions to be enforceable. A Florida-compliant Islamic Living Will must:

  • ✔ Be executed by a mentally competent adult
    You must be at least 18 years old and of sound mind at the time of signing.
  • ✔ Be signed in the presence of two witnesses
    At least one witness cannot be your spouse or a blood relative.
  • ✔ Be in writing
    Oral directives are not legally valid.
  • ✔ Be provided to your physician or medical facility
    This ensures medical staff know your wishes during a crisis.
  • ✔ Ideally include a Designation of Healthcare Surrogate
    This companion document authorizes the person you trust, preferably someone familiar with Islamic medical ethics, to make decisions if you are incapacitated.
  • ✔ Notarization
    Not required under Florida law but strongly recommended to prevent challenges or claims of improper execution.

Incorporating Islamic Principles Into Your Living Will

Islamic bioethical guidelines strongly influence medical decision-making. An Islamic Living Will may include:

1. Preservation of Life (Hifz al-Nafs)

You may specify that all treatments intended to preserve life should be considered, so long as they offer a reasonable expectation of recovery and are not excessively burdensome.

2. Avoiding Treatment That Only Prolongs the Dying Process

Islam teaches that when death is imminent and no medical intervention will restore meaningful recovery; it is permissible to decline extraordinary or futile treatments.

Your Living Will may direct:

  • No artificial life support where recovery is medically impossible
  • Withdrawal or refusal of life-prolonging procedures when death is inevitable
  • Comfort care only, including pain relief consistent with Islamic teachings

3. Pain Relief and Palliative Care

You can request pain relief even if it may unintentionally hasten death, provided the intent is not to cause death, consistent with Islamic ethics.

4. Organ Donation and Transplants

Different Islamic schools of thought allow organ donation under specific circumstances. Your Living Will can clearly express your position on:

  • Donating organs,
  • Receiving organ transplants,
  • Any religious conditions or restrictions.

5. Islamic Funeral and Burial Instructions

Although funeral directions do not make a Living Will legally binding, many Muslims include statements such as:

  • No embalming or autopsy unless legally required,
  • Timely burial in accordance with Islamic practice,
  • Notification of an Islamic center or imam.

Including these instructions can help guide family members in honoring your religious obligations.

Drafting an Islamic Living Will in Florida

Creating a document that is both legally enforceable and religiously compliant requires careful legal and religious consultation. A well-drafted Islamic Living Will typically involves the following steps:

1. Consult a Florida Estate Planning Attorney

To ensure the document meets all state requirements and aligns with Sharia principles, choose an attorney familiar with:

  • Florida’s advance directive laws,
  • Islamic bioethics and inheritance concepts, and
  • The proper drafting of medical directives for Muslim clients.

2. Clarify Your Religious and Medical Preferences

Discuss your beliefs and intentions regarding:

  • Life support
  • Resuscitation (DNR/DNI preferences, i.e., Do Not Resuscitate and Do Not Intubate)
  • Artificial nutrition and hydration
  • Organ donation
  • Levels of pain management

Your attorney can help translate these preferences into legally enforceable language.

3. Use Reputable Islamic Resources for Guidance

Many Islamic organizations provide worksheets and educational materials, including:

  • Local Masjids and Islamic centers
  • Islamic medical ethics organizations
  • National Sharia-compliant estate planning groups

These tools can help you prepare, but they do not replace a properly drafted legal document.

4. Execute the Document Properly

Sign the Islamic Living Will with two adult witnesses in accordance with Florida law. Consider notarizing the document for added security.

5. Distribute Copies to Key Individuals

Provide copies to:

  • Your healthcare surrogate,
  • Your primary care physician,
  • Your family,
  • Your attorney,
  • Your preferred Islamic center, if desired.

This ensures your wishes are known and honored in an emergency.

Why an Islamic Living Will Matters

Creating an Islamic Living Will provides significant benefits:

  • ✔ Ensures your treatment aligns with your faith
    Medical decisions will reflect Islamic bioethical principles.
  • ✔ Prevents confusion and conflict among loved ones
    Your family will not have to guess or debate your wishes.
  • ✔ Protects your legal rights
    Florida providers must follow a properly executed Living Will.
  • ✔ Provides peace of mind
    You maintain control over your medical care, even if you cannot speak for yourself.

Conclusion

An Islamic Living Will is an essential tool for Muslims in Florida who want to ensure that their medical treatment, especially in critical or end-of-life circumstances, reflects both Florida law and Islamic values. By thoughtfully planning ahead and working with a qualified estate planning attorney, you can safeguard your religious principles, reduce stress for your family, and secure dignified, faith-aligned medical care.

The foregoing is a brief and general overview of the topic and the need for specific and experienced legal and tax advice is emphasized.

If you have any additional questions regarding the foregoing or have any legal issues or concerns, please contact the law firm of CASERTA & SPIRITI in Miami Lakes, Florida.

Florida Estate Planning Checklist: The Essential Documents Every Florida Family Should Have

Planning your estate is not just about distributing assets, it is about protecting your loved ones, preserving your legacy, and making sure your wishes are honored under Florida law. Whether you are just getting started or updating an existing plan, this quick guide highlights the core documents every Floridian should consider.

1. Last Will & Testament

Your Last Will is the cornerstone of your estate plan. It allows you to:

  • Decide who inherits your assets and on what terms.
  • Name a guardian for minor children.
  • Specify your final wishes, such as burial or cremation.
  • Appoint a personal representative (executor) to handle your estate.

Florida requires two witnesses for a valid Last Will, however, notarizing the Will through a self-proving affidavit is a best practice that can simplify the probate process by creating an easier way to prove its validity later. A Last Will must be carefully drafted to comply with state law to avoid delays or disputes during probate.

2. Durable Power of Attorney (Financial & Property Management)

A Durable Power of Attorney (DPOA) authorizes a trusted person (your “Agent”) to act on your behalf in financial, business, or property matters, even if you become incapacitated.

Common Powers Include:

  • Managing bank accounts and paying bills
  • Handling real estate and investments
  • Filing taxes or signing contracts

Florida law does not permit “springing” powers of attorney—your DPOA is effective immediately upon signing, so choose your Agent wisely.

3. Health Care Surrogate Designation

This document lets you appoint someone to make medical decisions if you cannot communicate. Your Healthcare Surrogate can:

  • Speak with doctors and review records
  • Consent to or refuse treatments
  • Carry out your wishes during hospitalization or incapacity.

4. Living Will / Advance Directive

A Living Will, also called an Advance Directive, expresses your wishes about end-of-life care if you are terminally ill or permanently unconscious.

It helps your family and physicians know:

  • Whether you want life-sustaining treatment
  • Preferences for pain management, hydration, or feeding
  • Spiritual or organ donation requests

Florida Statutes (Chapter 765) govern Living Wills—these must be in writing, signed, and witnessed by two adults, with one of the witnesses not being a spouse or blood relative.

5. Revocable Living Trust

A Living Trust lets you transfer ownership of assets during your lifetime while keeping control as the trustee. Upon your death, assets in the Trust pass directly to your beneficiaries without probate.

Key Benefits:

  • Avoids Florida probate court
  • Maintains privacy of your estate
  • Allows controlled or delayed distribution to heirs
  • Can provide ongoing management if you become incapacitated

Florida couples can create either individual or joint trusts, which are ideal for couples seeking a smooth transfer of property.

6. Other Considerations

  • Beneficiary Designations: Keep life insurance, IRAs, and bank account designations current.
  • Digital Assets: Include email, cryptocurrency, and online accounts in your plan.
  • Funeral & Final Arrangements: Consider a written “Letter of Instruction” for family reference.

Get Professional Guidance

Florida estate planning laws are strict and technical—a single error can render your Last Will or Power of Attorney invalid. Working with an experienced Florida estate planning attorney ensures your documents comply with current statutes and reflect your specific goals.

The foregoing is a brief and general overview of the topic and the need for specific and experienced legal and tax advice is emphasized.

CASERTA & SPIRITI, PLLC. in Miami Lakes proudly helps Florida families create and update Last Wills, Trusts, and Powers of Attorney that offer peace of mind and long-term protection at affordable rates.

Naming a Special Needs Trust as Beneficiary

Naming a Special Needs Trust (SNT) as a beneficiary of an IRA or retirement plan as well as a Last Will or Trust that names the Special Needs Trust as a beneficiary can be a smart estate planning move, but it comes with complex tax implications that require careful consideration. The following is a breakdown of some key points covered in the article:

1. Coordinating Your Beneficiary Designations:

  • IRA and Retirement Accounts: These accounts generally pass to a named beneficiary directly, bypassing the Last Will. This means that if you name your child with special needs as a direct beneficiary of your IRA, the funds will go directly to them, which could disqualify them from receiving means-tested government benefits (like Medicaid or SSI).
  • Solution: Name the Special Needs Trust as the beneficiary of the IRA instead of your child. This ensures that the funds are available to support your child without impacting their eligibility for government benefits.

2. Stretching IRA Distributions and Tax Concerns:

  • If you name your estate or a charity as the beneficiary of your IRA, the distributions must occur quickly, often within five years of your death (before the Required Beginning Date, RBD), or over your remaining life expectancy (after RBD). This could result in a hefty tax bill because the distributions would be large and taxed as ordinary income.
  • Designated Beneficiary: A human beneficiary allows “stretch” payments over the person’s life expectancy, reducing the tax burden. A Special Needs Trust may qualify for this “stretch” if properly drafted and the IRS can “look through” to the individual with special needs as the designated beneficiary.

3. Pitfalls of Trusts as Beneficiaries:

  • Accumulation Trusts: These allow the trustee to retain IRA distributions in the trust for future use. However, if the trust names a charity or an elderly beneficiary as a remainder beneficiary, the IRS may shorten the payout period, disallowing the “stretch” option.
  • Conduit Trusts: These require immediate distribution of IRA funds to the beneficiary. Only the life expectancy of the primary beneficiary (i.e., the individual with special needs) is considered, making it easier to stretch the distributions over their lifetime.

4. Ensuring the Stretch for Special Needs Trusts:

  • The Special Needs Trust must be irrevocable at the time of your death, and all required documentation must be provided to the IRA custodian or retirement plan administrator.
  • Avoid naming non-human entities (such as charities) as beneficiaries if you want to maximize the “stretch” benefit. If a charity is named as a remainder beneficiary, the IRS will calculate the payout based on a zero-life expectancy, which leads to faster distribution and higher taxes.

5. Successor Beneficiaries:

  • If a surviving spouse is named as the primary beneficiary of your IRA, they can roll the funds into their own IRA, allowing them to name the Special Needs Trust as the contingent beneficiary. This preserves the “stretch” option for the Special Needs Trust after the spouse’s death.
  • Failing to roll over the account could result in accelerated distributions based on the spouse’s remaining life expectancy, which is likely shorter than that of the child with special needs.

6. Changes in Law and Future Risks:

  • The IRS could eliminate the “stretch” option entirely, as proposed in several presidential budgets, which would limit the stretch to five years for most beneficiaries. Given this possibility, it is important to stay informed and revisit your plan periodically.

Conclusion:

The rules for naming a Special Needs Trust as a beneficiary of an IRA or retirement account are complex. Improper designations can lead to significant tax consequences and jeopardize the availability of government benefits for your family member. It is essential to collaborate with an attorney who is well-versed in Special Needs Trusts and retirement planning to ensure the trust is structured to take full advantage of tax deferral opportunities while protecting your loved one’s benefits.

The foregoing is a brief and very general overview of the topic and the need for specific and experienced legal and tax advice is again emphasized.

If you have any additional Questions regarding the foregoing or have any legal issue or concern, please contact the law firm of CASERTA & SPIRITI in Miami Lakes, Florida. To discuss special needs trust planning, request a consultation or call (305) 463-8808. Please avoid submitting confidential information in an initial inquiry; contacting the firm does not establish an attorney-client relationship.

Cryptocurrency & Other Digital Assets in a Florida Estate Plan & Probate - Part 1

Cryptocurrency & Other Digital Assets in a Florida Estate Plan & Probate – Part 1

A growing number of individuals possess a considerable amount of cryptocurrency as well as other digital assets from email accounts and online cloud storage of files and photos NFTs. Some of these assets can hold great sentimental or even financial value to a person’s loved ones after their death. Despite this situation, many individuals fail to account for their digital assets when drafting an estate plan. Forbes Magazine estimates that the total global value of cryptocurrency is approximately $1.75 trillion this year. Despite not being widely understood by everyone, digital assets, including cryptocurrency, are an asset class which are likely to remain. This raises an important question: How is a digital asset such as cryptocurrency managed in probate? The brief answer is that there is no technical legal distinction between cryptocurrency and other “property” investments in probate; however, there are some distinct practical differences. The following is a general overview of the key aspects to understanding cryptocurrency as well as other digital assets in estate planning and probate in Florida.

When a person dies with estate assets, it is up to their family, specifically their Personal Representative or executor, to take an inventory of the assets within the estate and file it with the Florida Probate Court. But creating an inventory of a person’s digital assets is far more difficult than simply finding the items stored in their attic.

Without a digital asset estate plan, it will be far more difficult for your Personal Representative to identify and document a deceased party’s digital assets. They may be able to locate certain assets by accessing a household computer and reviewing saved passwords. However, other digital assets may be overlooked or simply lost if not properly documented in a digital asset estate plan. To avoid this, a Florida resident and their estate planning attorney should prepare a list of the digital assets, along with links to the apps or URLs used to access them and log-in credentials necessary to access the account.

What will happen to digital assets without an estate plan is that they may simply disappear. For example, Google recently announced that beginning December 1, 2023, it will be deleting unused accounts. Idle accounts that have been dormant for at least two years, including those that belonged to a deceased party, will be deleted to make space for future uploads. This affects Gmail emails and files stored in Google Drive, Docs, Meet, Calendar, and Photos, as well as some YouTube videos. To preserve those files, someone must log into the account at least every two years.

A Personal Representative acts as the fiduciary for one’s estate after death. The Letters of Administration issued by the Florida probate court can be used to access one’s bank accounts, talk to applicable financial advisors and insurance companies, and perform financial transactions such as selling real and personal property. Since 2016, that has included granting fiduciaries access to digital assets as if they were the account holder.

However, a few digital asset companies like Facebook or Google do not honor Letters of Administration easily. They may have their own processes for a person to designate a legacy contact for their accounts and may assert federal privacy laws preventing them from giving the Personal Representative or executor full access to the accounts without the decedent’s consent. If a person dies without naming a legacy contact, the Personal Representative may need to file a petition with the Florida Probate Court to enforce the Fiduciary Access to Digital Assets Act and gain access to the applicable online accounts. This process will increase the cost of estate litigation as the social media and digital asset companies seek to protect the deceased party’s privacy even when the decedent never wanted them to do it.

This access issue becomes especially complicated with blockchain technology and cryptocurrency assets. One of the unique aspects of cryptocurrency is that it is decentralized, i.e., there is no single entity overseeing and endorsing all the transactions. Instead, possession of Bitcoin or other crypto assets is represented by possession of a key. Without it, a digital wallet will be lost. Various estate planning attorneys and their clients have devised interesting ways to pass these keys to the intended beneficiaries without violating federal cybersecurity laws.

Without a plan in place, there may be no amount of estate litigation that will be able to save one’s digital assets if that digital key is lost. The cryptocurrency companies do not maintain records tying their users’ identities to their keys. That means there is no way for the probate court to compel discovery of the login credentials.

However, in other cases, a caregiver or other person with access to the deceased’s home may wrongfully take possession of the flash drive or paper one’s digital key is stored on. If they do, it could require estate litigation against them to get them to turn that property over to the personal representative so it can be distributed according to one’s wishes.

In 2014, the IRS issued a notice stating it would treat “virtual currency” like Bitcoin as personal property, rather than cash. In probate court, these assets are more like heirlooms than bank accounts. The distribution of digital currency within an estate administration case could trigger capital gains taxes based on the change in value between when the crypto assets were obtained and when they were transferred out of the estate.

This can also create problems in the estate’s accounting. Personal Representatives are required to account for all the financial transactions of the estate, including the distribution of assets to beneficiaries. However, in calculating the value of crypto assets, the personal representative will need to determine the “cost basis” of those assets based on when the deceased obtained them. Unless that person kept careful records of their crypto transactions, the estate may need to retain a financial professional to establish the change in those assets’ value over time. If the personal representative fails to do so, it could expose the family to estate litigation or even tax consequences related to the improper accounting for cryptocurrency.

Digital assets, including cryptocurrency and NFTs, represent a sizable portion of many people’s estates today. Without proper estate planning, these valuable and often irreplaceable assets can easily be lost. By preparing a comprehensive digital asset estate plan, a Florid resident can ensure that their personal representative can access, manage, and distribute these assets according to the decedent’s wishes. This planning will save one’s heirs time, effort, and potential legal battles while preserving the digital legacy. If a Florida resident needs assistance with cryptocurrency in probate or any other estate planning matter, contact an experienced Florida probate and estate planning attorney for expert guidance and support.

The foregoing is a brief and general overview of the topic (Part 1).
If you have any additional Questions regarding the foregoing or have any legal issue or concern, please contact the law firm of CASERTA & SPIRITI in Miami Lakes, Florida.

END OF PART 1

Avoiding Probate Does Not Have to Involve a Trust in Florida – Use a Lady Bird Deed

Avoiding probate in Florida can be a complex endeavor, but it does not always require the use of a revocable living trust. There are alternative methods that can achieve similar results, and one such method is the “Enhanced Life Estate Deed,” also known as the Ladybird Deed.

It is a common misconception that assets placed in a revocable living trust are completely protected from creditors’ claims. In reality, most jurisdictions, including Florida, allow creditors of a decedent’s estate to reach assets held in a revocable living trust. This can come as a shock to many Florida residents who believe that a revocable living trust provides ironclad protection. A person’s transfer of his/her homestead or primary residence into a revocable living trust may turn it into a counted assets for purposes of applying for Medicaid as well as possibly jeopardizing or limiting the homestead tax exemption and other homestead protections.

Despite this limitation, there are still significant benefits to using a revocable living trust as part of an estate plan. One of the primary advantages is the ability to set specific instructions for the distribution of assets upon death. This can include setting ages for beneficiaries to inherit, providing for the care of family members with disabilities, and ensuring that assets are distributed in an orderly manner.

Additionally, a revocable living trust can help avoid the probate process, which can be time-consuming and expensive. By placing assets in a trust, they can pass directly to beneficiaries without the need for court involvement. This can provide greater privacy and efficiency in the distribution of assets after death.

However, for those looking to avoid probate without the use of a revocable living trust, an Enhanced Life Estate Deed, also known as a Ladybird Deed, can be an effective and potentially simpler and cheaper alternative. This type of deed allows the property owner to retain control and flexibility over the property during their lifetime while ensuring that it passes directly to named beneficiaries upon their death.

With an Enhanced Life Estate Deed, the property owner retains an “enhanced” life estate, allowing them to maintain control and make decisions about the property during their lifetime. Meanwhile, the beneficiaries are named to receive the remainder interest in the property upon the owner’s death and not before! This arrangement effectively avoids probate because the property passes directly to the beneficiaries, known as Remaindermen, outside of the probate process.

One of the key benefits of using an Enhanced Life Estate Deed is that the property owner retains control and flexibility over the property. They can sell, convey, lease, or mortgage the property as they see fit without needing the consent of the beneficiaries. This level of control sets it apart from traditional life estate deeds, where the owner relinquishes control over the remainder interest.

Another advantage is that the property passes free and clear of the decedent’s creditors’ claims, provided it is given to surviving lineal descendants. This protection can be crucial for safeguarding the property from potential creditor issues that may arise after the owner’s death.

However, it is essential to proceed with caution when creating an Enhanced Life Estate Deed or Lady Bird Deed. Using the wrong language or making mistakes in the deed could lead to unintended consequences. Therefore, seeking the guidance of an experienced attorney who understands these legal nuances is highly recommended.

In addition to using Enhanced Life Estate Deeds for real estate, there are other methods for avoiding probate, such as properly titling bank accounts and investment accounts. Transfer on Death (TOD) or Paid on Death (POD) designations or In Trust for (ITF), or generally, designation of beneficiaries, allow account holders to name beneficiaries who will inherit the assets directly upon their death, bypassing the probate process.

While it may be tempting to handle these matters without legal assistance, it is crucial to recognize the complexities involved and the potential risks of do-it-yourself (DIY) estate planning. Consulting with a knowledgeable attorney can ensure that one’s estate plan is properly structured to achieve their goals and protect their assets for future generations.

Ultimately, whether to use a revocable living trust or an Enhanced Life Estate Deed (Lady Bird Deed) depends on the individual’s specific goals and circumstances. Consulting with an experienced estate planning attorney can help ensure that the chosen strategy aligns with their needs and objectives while providing the necessary protection for themselves and their loved ones.

The foregoing is a brief and general overview of the topic. If you have any additional questions regarding the foregoing or have any legal issue or concern, please contact the law firm of CASERTA & SPIRITI in Miami Lakes, Florida.

INTESTACY-Dying Without a Will in Florida

If a Florida resident dies without a Last Will & Testament, their assets will be transferred to their closest relatives under state “intestate succession” laws. The following is a brief summary of how intestate succession works in Florida.

Only assets that go through probate are impacted by intestate succession laws. Many valuable assets are not subject to probate, and therefore they are not affected by intestate succession laws. Here are some examples: property one has transferred to a Living Trust; life insurance proceeds with a named beneficiary; funds in an IRA, 401(k), or other retirement account with a named beneficiary; securities held in a transfer-on-death account; real estate for which one has a transfer on death deed or Lady Bird Deed; vehicles for which you have a transfer on death registration; payable-on-death bank accounts, or property a person owns with someone else in joint tenancy with right of survivorship, or tenancy by the entirety (i.e., as spouses).

These assets will be transferred to the surviving co-owner or to the beneficiary one has named, whether or not a Last Will exists. However, if a person possesses or creates a Last Will and none of the named beneficiaries are alive to take the property, then the property could end up being transferred according to Intestate succession.

Florida Statute Sections 732.101-.109 cover this process of Intestate succession. When someone passes away without a Last Will, or Trust, all assets go to the closest relatives or “next of kin.”

The heirs follow a specific order in Florida:

  1. The first to inherit is the surviving spouse. There must be a valid marriage to be a surviving spouse. If there are no children, the spouse gets everything and there is no waiver of rights pursuant to a signed Prenup or Postnup or comparable document.
  2. Next in line are the children. If a child dies before the parent, then a grandchild may inherit a portion of the estate. Children must be legally adopted or biological children to fit in this category. Step-children are not included.
  3. If the decedent dies without a spouse or children, then, the decedent’s parents are next in line to inherit the estate.
  4. If none of the above are alive, then the deceased’s siblings would divide the estate.

Certainly, family units may be difficult and complicated in today’s world. For example, usually the surviving spouse receives or inherits everything. However, if the decedent has children from a previous marriage, the surviving spouse may get half the estate and the other half goes to the child or children from the prior marriage(s). Basically, each scenario may have difficulties and complications.

Proper estate planning can prevent intestate succession. A comprehensive and even a proper basic estate plan includes a Last Will and/or Trust, as well as a Powers of Attorney for financial and healthcare needs. These essential documents protect all Florida residents and their families and tend to conserve funds and assets.

How many people want State law to determine how their hard-earned life’s assets are distributed? How many individuals want to pay the State money after their death?

Properly written and executed estate plans reduce estate taxes, eliminate lengthy probate proceedings, avoid family disputes, set up care for minor children, and fulfill the deceased party’s wishes.  No one can anticipate the future, however, thoughtfully planning ahead provides a sense of peace of mind.

It is important to note that intestacy does not mean that the State of Florida owns or will acquire the property of the deceased.  This term simply means that the Probate court is required to invoke a specific process to determine who receives the deceased individual’s assets.

This process may differ depending on the state where the deceased party resided at the time of death.  Florida has a complex and detailed process in determining who receives these assets.  Usually, the surviving spouse is the first to inherit the subject property. There must be a valid marriage to be a surviving spouse. If there are no children, the spouse receives everything.

Since the process regarding intestate succession is very involved, it is vital to work with an attorney who is experienced with probate cases. To avoid confusion and disputes among potential beneficiaries or heirs and ensure that assets are properly distributed according to state law, one should employ an experienced attorney.

The foregoing is a brief and general overview of the outcome if no estate plan is established in Florida. 

If you have any additional Questions regarding the foregoing or have any legal issue or concern, please contact the law firm of CASERTA & SPIRITI in Miami Lakes, Florida.

Capacity to Make a Will or a Power of Attorney in Florida-Part 1

With millions of people having a form of dementia across the U.S. and the world, Estate Planning attorneys need to assess their potential clients to ascertain whether they are still capable and should be given the opportunity to contribute to and have input in their own lives as well as the lives of those around them. It is important to understand their changing needs as their disease advances, but even those with the most severe cases can still take part in an important way in the world around them.

The term “lucid intervals” comes into play. These intervals are moments of clarity for people with degenerative brain diseases. In these moments of clarity, they may regain many of their memories and mental functions. It is important to not only recognize these moments but also to give them credence.

There is a study by the National Library of Medicine, which goes into the various levels of capacity people may exhibit and ultimately states that “Capacity to make one’s own decisions is fundamental to the autonomy of the individual.” Consequently, there should be a plan for the moments when capacity improves or stabilizes.

There are varying levels of capacity for those with degenerative brain diseases, and medical professionals and loved ones should play a role in recognizing those levels of capacity without bias.

For example, “sundowning” is the process of medical or psychological conditions worsening as the day goes on, which is essentially named for the time period when the sun goes down or after dusk. If a loved one experiences sundowning, should decisions made earlier in the day during the more “lucid” period be invalidated because of a later lack of clarity?

Florida families need to empower their loved ones by providing them with the proper channels to express themselves and contribute to their own lives. Awareness should be raised on the abilities the elderly adult or loved one retains while battling any form of dementia.

After a diagnosis of Alzheimer’s disease or another type of dementia, a family has much to process and consider. In addition to dealing with the emotions that reasonably flow from this diagnosis, families must also make arrangements with the diagnosed elder adult in order to make plans for their current and future needs.

This situation can appear over-whelming, however, it is crucial that a family uses the early stages of the disease to fully understand the diagnosed elder adult’s wishes and get their input for moving forward.

It is much easier for everyone to be on the same page regarding a Power of Attorney as well as a Last Will and/or Advance Directives long before it or they become necessary because obtaining said Power of Attorney as well as other documents when the elder adult in question is already well into the disease process is more time consuming and difficult.


A Power of attorney is a legal document which allows someone to act on behalf of someone else regarding healthcare or financial decisions. There are many types of powers of attorney, each of which serves a unique or specific purpose. However, a Durable Power of Attorney is the most common for elderly adults.

Selecting who has Power of Attorney is a weighty decision. By Florida law, the person who is selected is called the Agent. This person should be a trustworthy and competent adult who is willing and able to manage complex medical and financial decisions and responsibilities on behalf of the diagnosed or incapacitated adult (the Principal). A financial institution that has trust powers [like a bank or trust company], so long as it has a Florida location and is authorized to conduct business in the state of Florida, can also be named an Agent.

At times, families choose to split power of attorney duties so that no one person is in charge of every decision. In these cases, they divide duties into healthcare decisions and financial decisions, creating two powers of attorney, one for each category.

Ideally, elders or any adult planning on a power of attorney should name their trusted Agent and have the papers drawn up and executed prior to any medical crisis, including a dementia diagnosis. However, if a loved one has not yet been diagnosed with dementia, those family members together with the subject adult can work together to name an Agent and execute a valid the power of attorney.

In general, a person with dementia can sign a power of attorney if they have the capacity to understand what the document is, what it does, and what they are approving. Most seniors living with early stages of dementia are able to make this determination.

If there is no power of attorney designation, and the older adult is further along in the disease’s process, the matter can get more complicated. If an older adult is unable to understand the power of attorney document and process, the family will need to enlist the aid of the local court whereby a judge can review the case and grant someone in the family (or a court appointment) the designation of conservator or Guardian. A conservatorship or guardianship allows the person or public guardian named by the court to make decisions about the person’s finances or other decisions. A guardianship allows the person named by the court to make decisions about the person’s healthcare. This procedure may be burdensome but can become necessary and may be the only way to advocate for a loved one and their wishes.

The Article will continue at a later date!

If you have any additional Questions regarding the foregoing or have any legal issue or concern, please contact the law firm of CASERTA & SPIRITI, in Miami Lakes, Florida.